Telephone:
0191 695 9493

Email:
info@northeastequityrelease.co.uk

How Does Equity Release Work?

Equity Release is the umbrella name for products that provide consumers with a way of releasing the wealth tied up in their property without necessarily having to sell it and move to another home.

With a lifetime mortgage, you can continue to own your home

Continue To Own Your Home

We can help you find a lifetime mortgage with a fixed interest rate

Lifetime Fixed Interest Rates

Icon of a scale.

No Negative Equity guarantee

Icon of coins.

No Income Assessment

With a lifetime mortgage, you can continue to own your home

Stay In Your Home For Life

We can help you find a lifetime mortgage with a fixed interest rate

No Credit Checks

We are your Equity Release Experts.

Equity Release is the umbrella term used for a range of financial products that allow homeowners to release their wealth tied up in their property without necessarily having to sell it and move. As specialist equity release advisors, we help homeowners understand how equity release works and help them access their equity safely and confidently.

Are you looking for help with Equity Release?

As equity release experts; let’s start at the beginning. There are two main types of Equity Release: Lifetime Mortgages and Home Revision Plans. Both of these are regulated by the Financial Conduct Authority, meaning any adviser recommending them must meet strict standards for sustainability, transparency and ongoing advice.

The most popular type of Equity Release is a Lifetime Mortgage, this allows homeowners to retain full ownership of their home, and this is the only type of equity release plan we recommend.

A Lifetime Mortgage lets you release equity from your home, which is the value of your property minus any outstanding mortgage or other secured lending.

Because the funds are yours in the first place, a Lifetime Mortgage is a simple way of releasing your equity and the money is tax free and can be spent on anything you like. There are no mandatory monthly repayments, although you can opt to pay some or all of the interest, or make capital repayments.

The other type of equity release is a Home Reversion Plan, where customers sell part or all of their home in exchange for a cash lump sum while retaining the right to remain in it, typically rent-free. We do not provide advice on these products.

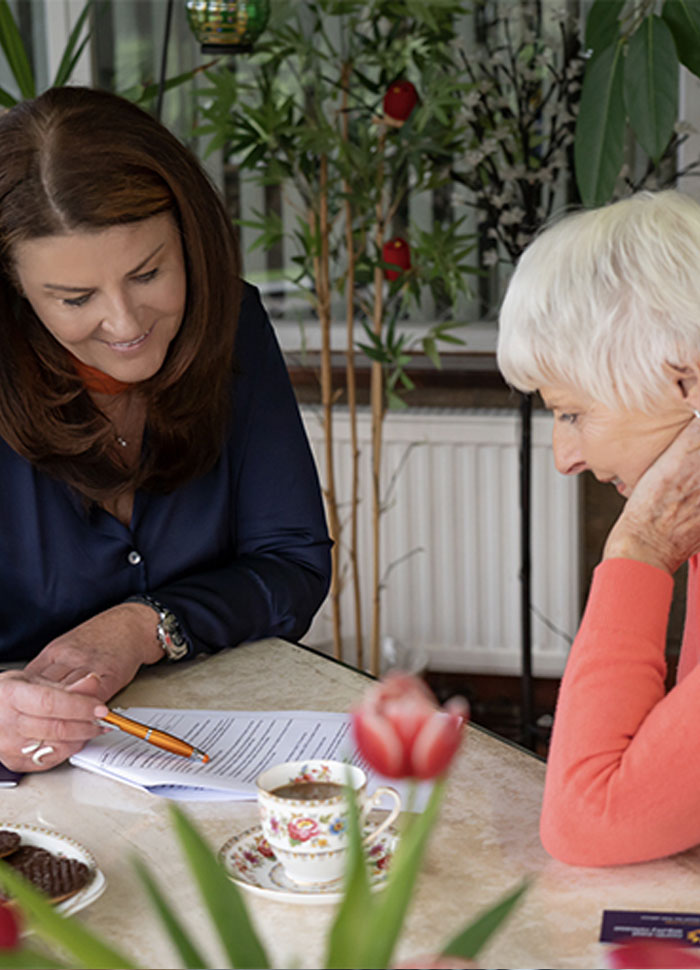
Photo of Joanne explaining details from a equity release contract with a client.

What does an Equity Release Expert Do?  

As equity release advisors, our role is to help you understand the ins and outs of Equity Release and we are here to help you navigate the tricky details which can feel overwhelming, we are here to guide you through the whole process, not just to explain products. From checking whether you’re eligible to explaining how the different products work, we take the time to understand your personal situation and make sure you have a full understanding.

As experienced Equity Release experts, we have access to a wide range of plans from leading providers and we will search the whole market to find the most suitable, lifetime mortgage for you. If you’re looking to release a lump sum, set up a drawdown facility, or simply explore your options, we are here to help you compare features, interest rates, and flexibility, so you can make an informed choice with confidence.

Working with qualified equity release advisors  means every aspect of your situation is considered and you are not relying on generic guidance or trying to interpret fine print alone. You’ll have peace of mind knowing you’ve had expert support from start to finish and that your long-term goals, family plans, and future comfort have all been factored in.

Is Equity Release Right for you?

Equity Release can be a helpful financial solution for many people, but it’s not always the right choice for everyone. That’s why speaking to our experienced equity release experts is so important.

We will take the time to understand your full situation, from your financial goals and family plans to your long-term needs. We explain the pros and cons in simple, honest terms and talk you through all the available options, including alternatives like downsizing, retirement interest-only mortgages, or using other savings.

There’s no one-size-fits-all answer when it comes to equity release. Our expert advice is designed to help you weigh up what’s right for you, not just now, but for the years ahead. Whether you’re looking to boost your retirement income, help a family member onto the property ladder, or simply want to explore your options, we are here to guide you.


Common Questions Answered by Our Equity Release Expert

Do I still own my home with Equity Release?

Yes. With a lifetime mortgage, you retain full ownership of your home. The loan, plus any accrued interest, is repaid when the property is sold, typically upon death or moving into long-term care.

How much can I borrow through Equity Release?

The amount depends on several factors, including your age, the value of your property, and your health. Generally, the older you are and the higher the property value, the more you can release. This is where we, as Equity Release Experts, can help you get a full understanding of what is available to you.

Can I move home after taking out a lifetime mortgage?

Yes. Many equity release plans approved by the Equity Release Council allow you to move to a new property, provided it meets the lender's criteria. The loan can be transferred to the new home. This is something that depends on the mortgage. We will work with you so you know your plan.

What happens to my Equity Release when I pass away or move into care?

Upon death or moving into long-term care, your property is typically sold, and the proceeds are used to repay the loan and any accrued interest.

Are there risks with Equity Release?

While equity release can provide financial flexibility, it may reduce the value of your property. Interest can accumulate over time, increasing the amount to be repaid. It's crucial to speak to an Equity Release expert to see if it's the right option for you.

What is the ‘no negative equity guarantee’?

This guarantee ensures that your estate will never be liable to repay more than the value of your home when it's sold at its true market value, even if the debt exceeds the property's value. This is a standard feature of plans approved by the Equity Release Council.

Can I repay my Equity Release loan early?

It depends on your plan, several allow for early repayment, but this may incur early repayment charges. We will discuss the most suitable plan for your personal circumstances.

What are the costs involved in setting up Equity Release?

Costs can include arrangement fees, legal fees, valuation fees, and adviser fees. Generally there are no upfront fees at all. We will provide a detailed breakdown of all costs involved.

If you have any more questions, please give us a call and our Equity Release experts will be more than happy to advise.